

When an unexpected bill lands before payday, the real question is not simply whether an app can move money quickly. It is whether the service fits your income schedule, your account setup, and your ability to repay without turning a small gap into a recurring problem. I tested B9: Cash Advance with that decision in mind, treating it as a practical finance tool rather than a magic fix for every cash shortage.
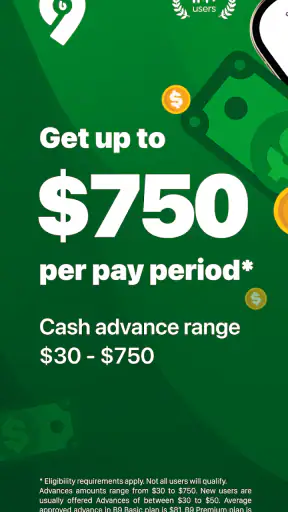
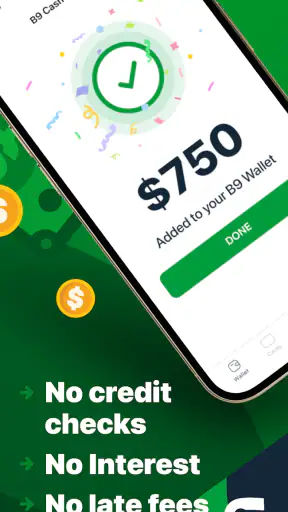
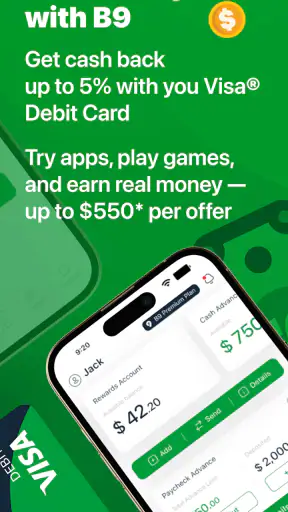
B9 is a free finance app from B9 - Get Your Paycheck Early. Its central idea is straightforward: eligible users can request access to part of their paycheck before the normal payday. That makes it most relevant to people whose income is dependable but whose bills arrive at inconvenient times. It is less suitable for someone looking for long-term borrowing, credit-building, or a way to solve a permanent mismatch between income and expenses.
The app has reached over one million installs and holds a 4.6 average from around eighteen thousand ratings, with roughly seven thousand five hundred written reviews. Those figures suggest that early-pay access is a meaningful use case for many people, but they should not replace a personal check of the terms shown during signup and each advance request. My experience is that this kind of product rewards careful reading more than impulsive tapping.
How I Decided Whether B9 Was a Good Fit
The first question is income timing, not urgency
I would begin by asking why the money is needed early. If the problem is a one-off timing issue—such as a utility payment arriving shortly before a regular paycheck—B9 may be worth considering. If the same shortfall appears every pay period, an advance can hide the underlying problem while making the following paycheck feel smaller. That distinction matters more than the app’s clean interface or quick onboarding.
A useful personal test is to write down the next expected paycheck, the amount already committed to rent and essentials, and the date the advance would need to be repaid or reconciled. I would not request money until I could explain exactly how the next pay cycle remains workable. This simple step is one of the most important safeguards because early access changes timing; it does not create additional income.
What I looked for during setup
With a financial app, convenience is only half the experience. I paid attention to how clearly B9 explains eligibility, the amount available, the timing of a transfer, and any cost or condition attached to the particular request. These details can vary by user and situation, so the screen presented immediately before confirmation deserves more attention than the promotional promise of getting paid early.
I also treated account connection and identity checks as part of the decision, not as annoying steps to rush through. A paycheck advance service needs enough information to establish income and direct funds correctly. Before proceeding, I would make sure the linked account is the one I actually use for payroll and that notifications are enabled. If an advance is approved but the destination account is outdated, the convenience disappears quickly.
The everyday scenario where it makes sense
Imagine a worker paid on a predictable schedule who has a necessary prescription or a car repair due two days before payday. Waiting may create a late fee or prevent them from getting to work. In that narrow situation, B9 can serve as a bridge: request only what is needed, confirm the repayment impact, and return to the normal budget after payday.
I would avoid using the full available amount merely because it appears on screen. A smaller advance reduces the pressure on the next paycheck and makes it easier to keep money aside for groceries, transportation, and automatic payments. The most responsible workflow is to decide the required amount before opening the app, then compare that amount with what B9 offers rather than allowing the available limit to set the budget.
Three practical habits that improve the experience
- Check the confirmation screen every time. Do not assume that a previous request tells you everything about a new one. Review the amount, arrival timing, and any displayed charge or condition before accepting.
- Use a separate “next payday” note. Record the advance and the amount that must remain available after payday. This prevents the app from becoming invisible inside a busy banking history.
- Keep a small timing buffer. If your employer’s deposit occasionally arrives later than expected, do not schedule essential payments around the earliest possible arrival. Early-pay tools help with timing, but they cannot remove every banking or payroll delay.
These habits reveal an important trade-off. B9 can reduce the stress of waiting, but it also asks the user to manage cash flow more actively. Someone comfortable tracking dates and balances may find that manageable. Someone already missing payments or losing track of account activity may need a budgeting solution first.
Where B9 feels strongest
The strongest part of B9 is its focus. It is not trying to be a full investment platform, a traditional credit card, or a broad banking replacement. Its purpose is easy to understand: help eligible users access paycheck money before the usual payday. That narrow purpose makes the app easier to evaluate than a complicated financial product with many unrelated tools.
I also like the psychological advantage of a dedicated advance workflow. When a cash gap is urgent, searching through a conventional bank app for an overdraft option or applying for a personal loan can feel disproportionate. B9 presents a more targeted route for a short-term timing problem. That does not automatically make it cheaper or safer, but it can make the decision more visible and deliberate.
The free download lowers the barrier to exploring the service, and the Everyone content rating makes it broadly accessible from an app-store perspective. The current version is 3.71.0, and the app supports Android 8.0 and later. For someone using an older Android phone, checking operating-system compatibility before planning around the service is sensible; an urgent financial tool is not useful if the device cannot run it.
What I would verify before requesting money
I would not treat “free” as a complete cost description. It means there is no purchase price to download the app, but a financial request can still display its own conditions. Before confirming, I would look for any optional expedited delivery, membership-related wording, transfer charge, or other amount shown in the request flow. If the total is not clear, I would pause rather than assume the advance is costless.
I would also check whether the requested amount solves the actual problem without creating a second one. For example, taking enough to cover a bill but leaving too little for the next automatic debit can produce another shortage. A good advance is one that fits inside the following pay cycle; a bad one simply moves the emergency a few days forward.
Where a different category may fit better
B9 is not the only answer to an early-cash problem, and its focused design will not suit everyone. A conventional bank overdraft may be more convenient for a customer who already has a strong relationship with their bank and needs a payment to clear automatically. The downside is that overdraft rules and charges can be difficult to predict, so I would compare the exact cost rather than choosing by habit.
A personal loan is usually a better category for a larger, planned expense that cannot be repaid from the next paycheck. It involves more commitment, but that can be healthier than repeatedly taking small advances for the same obligation. For a recurring budget deficit, a spending plan, debt counseling, employer payroll support, or an income adjustment may address the cause more effectively than any advance app.
Credit cards can offer a reusable payment method, but they may encourage a balance to roll forward. B9 is more narrowly tied to paycheck timing, which can be an advantage when the need is genuinely short-lived. On the other hand, a person seeking rewards, purchase protections, or a longer repayment structure should look at the credit-card category instead, while carefully considering interest and fees.
Even simply asking a bill provider for a changed due date can be a better alternative. That option may take a conversation rather than an app request, but it avoids borrowing altogether. I would especially consider it when the same bill repeatedly falls just before payday. Fixing the schedule is more sustainable than paying to bridge the same gap month after month.
Who should use caution or skip it
I would be cautious if my income were irregular, seasonal, or already committed to several automatic withdrawals. The value of a paycheck advance depends on a dependable future deposit. If that deposit is uncertain, the advance may become a much heavier obligation than expected.
I would also skip B9 if I needed a substantial amount, wanted to build a credit history, or needed a multi-month repayment plan. Its early-paycheck concept is not a substitute for a traditional loan assessment or a complete budget repair. Likewise, anyone uncomfortable linking financial information or reviewing digital confirmations should choose a method they can understand and monitor confidently.
Another overlooked issue is repetition. The first request may feel harmless because it solves a real emergency. The risk appears when every payday is partially spent in advance, leaving the user to borrow again before the next deposit. I would set a personal rule: use the service only for a defined, temporary timing problem and stop if the same category of expense returns repeatedly.
The cost of switching from another solution
Moving to B9 from a bank overdraft is not just a matter of installing another app. I would need to learn its eligibility flow, confirm how paycheck information is handled, understand when funds arrive, and adjust the way I track repayment. That learning cost is small compared with a long loan, but it still matters when money is needed immediately.
Switching away from B9 has a similar practical cost. Any scheduled bills, reminders, or personal budgeting notes built around early access need to be changed. I would first let the current cycle settle, confirm that no expected advance is being relied upon, and then return to ordinary payday planning. Closing or abandoning a financial app without checking the last transaction is an avoidable mistake.
The best comparison is therefore not “which app is fastest?” It is “which method leaves me with the clearest next paycheck?” If a bank arrangement, a delayed bill, or a small emergency fund produces a more predictable balance, that option may be better even if B9 is easier in the moment.
My recommendation after using it
I recommend B9 for a specific kind of user: someone with regular paycheck income who occasionally needs to bridge a short gap, is willing to inspect the request details, and can repay without sacrificing essentials after payday. For that person, the app’s focused purpose and free entry point make it a reasonable tool to investigate.
I would not recommend treating it as extra spending power. The most useful way to use B9 is to define the emergency first, request the smallest workable amount, record the effect on the next paycheck, and review every displayed condition before confirming. Those four steps turn a quick-money feature into a controlled cash-flow decision.
Overall, I see B9 as a practical option rather than a universal financial solution. Its 4.6 average and popularity show that many users find value in early paycheck access, but personal suitability depends on income reliability and repayment discipline. If your problem is timing, it may help. If your problem is that monthly expenses consistently exceed income, I would choose budgeting support, a renegotiated bill schedule, or a more structured financial product instead.
For a short-term paycheck gap, B9: Cash Advance is worth considering, provided you read the final request details and keep the next payday in view. That is the line I would use: helpful as a controlled bridge, risky as a routine.


